One price, both kits
E-Invoicing + VAT Credit Pair
USD 49
Single-business licence. Bought separately, the two kits are USD 39 (e-invoicing) and USD 29 (VAT credit), USD 68 in total.
Available soonWhat you get
- 1 Excel workbook with both kits' tabs
- E-invoicing guide (8 pages, PDF)
- VAT credit guide (6 pages, bilingual PDF)
Files: UAE-eInvoicing-VATCredit-Pair-v1.0.2.xlsx, UAE-eInvoicing-Guide-v1.3.2.pdf, UAE-VAT-Credit-Guide.pdf
One-time payment in USD. Checkout is run by Lemon Squeezy, our merchant of record, which adds any VAT or sales tax due in your country and emails your receipt and download link. Nothing physical is shipped. No subscription.
Preview
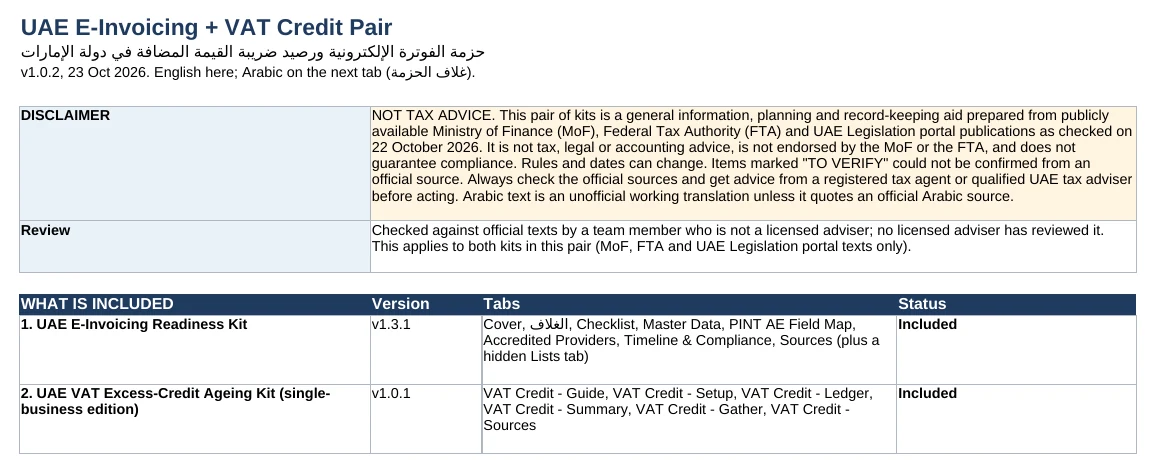
The pair contains the same tabs as the two kits; see the previews on the e-invoicing kit and VAT credit kit pages. The pair ships a blank VAT ledger and no separate sample file.
1. UAE E-Invoicing Readiness Kit
- 30-step checklist from scope to go-live, each step tied to the article or MoF guideline behind it.
- Pick your revenue category once and the checklist fills in the statutory dates (Ministerial Decision 244 of 2025, as amended).
- 300-row customer/supplier master-data clean-up with a 15-digit TRN format check.
- All 265 PINT AE invoice business terms in English and Arabic, with the 51 MoF mandatory fields flagged.
- The 70 providers on the MoF accredited list as of 22 Oct 2026, with blank comparison columns.
- Timeline and the list of violations, each with its legal source. No penalty amounts.
2. UAE VAT Excess-Credit Ageing Kit (single-business edition)
- Ledger of excess-credit balances by tax period, with the expiry date under each of the two laws that count the 5 years and a Recommended act-by (earlier date): a cautious reading, not the legal deadline.
- Traffic-light status per row, with flags where the two counts disagree. The tracker never tells you that you qualify.
- A checklist of records to gather and questions to raise with your registered tax agent. Not a filing procedure.
The rules it follows
From 1 January 2026, an excess VAT credit that is not refunded or used lapses 5 years from the end of the tax period it arose in, not from the purchase or filing date (VAT Decree-Law Art. 74(3), as amended by Federal Decree-Law 16/2025). A one-time window (Federal Decree-Law 17/2025 Art. 3(1)) covers balances whose 5-year period expired before 1 Jan 2026 or expires within one year of that date, measured on the Tax Procedures Law count. The law sets the window as a period not exceeding one year from 1 Jan 2026. It states the period, not a calendar date; treating 31 Dec 2026 as the last day is the cautious reading. Confirm your own timing with the FTA or your registered tax agent.
Within the window you may ask the FTA either to refund the balance or to use it to pay tax liabilities or administrative penalties; both requests have the same deadline.
Not modelled: balances that arise late, from an FTA decision or otherwise, may have extra time under Tax Procedures Law Art. 38(3)–(4): one year or 90 days from the date the balance arises. The tracker does not calculate this; enter your own start date in the override column and check with a registered tax agent.
Who it's for
UAE SMEs (mostly under AED 50 million revenue), finance managers and bookkeepers running these tasks in-house.
Format
.xlsx, no macros, no array formulas. Excel 2010+ / Microsoft 365, LibreOffice. Single-business licence; do not resell or redistribute. Rules checked 22 October 2026.
How this was made: the workbooks, formulas, guides and translations were drafted with the help of AI tools. Our team, who are not licensed tax advisers, compared the rules with the official FTA, MoF and UAE Legislation texts. No licensed tax adviser or registered tax agent has reviewed the kits.
Arabic: the Arabic text is a working translation; native-speaker review is pending. Where an official Arabic legal text exists, it prevails.